Home improvements and major repairs
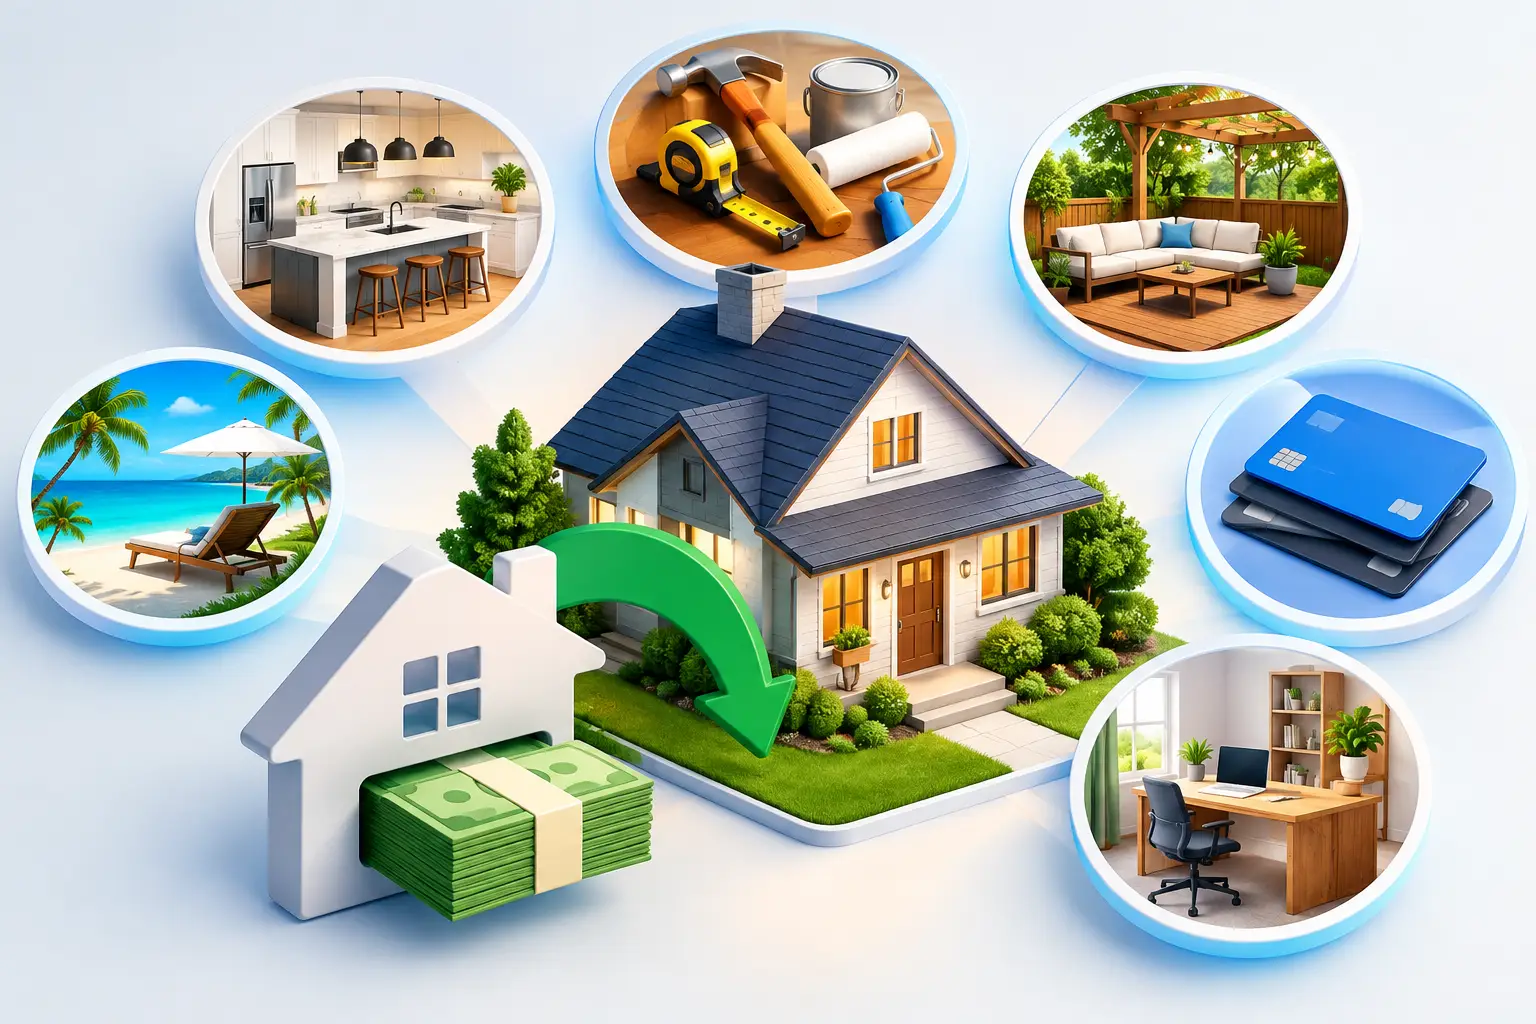
Renovations are one of the most common reasons homeowners consider a HELOC. A kitchen update, roof replacement, HVAC system, accessibility modification, or needed plumbing repair can protect the condition and usefulness of your property. Certain projects may also add market appeal, although no renovation guarantees a dollar-for-dollar increase in home value.
The distinction between a need and a want matters. Replacing a failing roof or repairing water damage is usually easier to justify than borrowing heavily for finishes that do not fit your budget or neighborhood. Get written contractor estimates, include a contingency for surprises, and borrow only what the project requires.
A HELOC can work particularly well when bills arrive in stages. Rather than paying interest on a full project amount from day one, you may be able to draw only when deposits, materials, and completed work are due. Terms vary by lender, so confirm how draws, interest, and repayment work before moving forward.
High-interest debt consolidation
Using home equity to consolidate high-interest credit card balances can lower monthly interest costs for some homeowners. It may also simplify multiple due dates into one payment. But the lower rate does not erase the debt. It changes the type of risk involved.
Credit card balances are generally unsecured. A HELOC is secured by your home. If you cannot keep up with payments, the consequences can be much more serious. Consolidation makes the most sense when you have addressed the spending or income issue that created the balances, have a firm repayment timeline, and will not run the cards back up after paying them off.
Compare the full cost, not only the advertised rate. HELOCs often have variable interest rates, which means your payment can rise if rates increase. Ask about closing costs, annual fees, early closure fees, minimum draw requirements, and whether the lender can change or freeze available credit under conditions described in the agreement.
Education or career-related expenses
A HELOC may be worth considering for a credential, licensing requirement, training program, or equipment that supports a documented career opportunity. The key is being conservative about projected income. A program should have a credible connection to higher earnings, job stability, or a necessary professional qualification.
For some borrowers, federal student aid or employer tuition assistance may offer stronger protections or more favorable terms. Compare those options first. Home equity financing should not be the automatic answer simply because it is available.
A necessary major purchase
Some large purchases cannot be delayed indefinitely. Replacing an unsafe vehicle, adapting a home after a disability, or covering an essential household system can be reasonable uses for a HELOC when other financing is more expensive or less workable.
The purchase should be necessary, priced carefully, and aligned with your ability to repay. Borrowing against your home for a depreciating asset deserves extra caution. A car, for example, may lose value quickly while your HELOC balance remains. Keep the borrowing amount controlled and avoid extending repayment longer than the useful life of what you are buying.
When a HELOC Can Help With Investment Activity
Some homeowners use a HELOC for an investment property down payment, repairs on a rental, or a business opportunity. This can be appropriate for experienced borrowers who understand the downside as clearly as the potential return.
Investment plans can face vacancy, market declines, construction delays, or lower-than-expected revenue. You still owe the HELOC payment if the investment does not perform. Avoid relying on optimistic projections or assuming a property will always appreciate. A strong plan includes cash reserves, a repayment path that works without best-case returns, and a clear limit on how much home equity you are willing to risk.
For most households, using a HELOC to buy stocks, cryptocurrency, or other volatile investments is far more speculative. Market losses do not reduce what you owe, and a variable HELOC rate can add another layer of uncertainty. This is usually not a prudent match for funds secured by your primary residence.
Uses That Usually Deserve a Pause
A HELOC is not free cash, even if the available line is substantial. Vacation spending, routine living expenses, luxury purchases, and recurring bills are often warning signs. These costs do not create lasting value and may indicate that the underlying budget needs attention first.
It is also wise to pause before using a HELOC to cover an ongoing income shortfall. Borrowing may provide temporary breathing room, but the balance can grow quickly when there is no reliable way to repay it. In that situation, reviewing household expenses, income options, and other forms of assistance may be more protective than converting a short-term cash-flow problem into debt secured by your home.
How to Decide Whether the Funds Fit Your Plan
Start by defining the exact amount you need and the maximum amount you are willing to borrow. Then build a repayment estimate using a rate that is higher than the current quoted rate. Since many HELOCs carry variable rates, planning only around the lowest possible payment can leave little room for change.
Next, look at your total monthly obligations. Include your mortgage, property taxes, insurance, existing debt payments, and the potential HELOC payment after the draw period ends. Some HELOCs allow interest-only payments during the draw period, followed by a repayment period that requires principal and interest. That later payment can be significantly higher.
Finally, compare offers based on terms that affect your real cost and flexibility. A lender will make the final approval decision based on its own guidelines, including your equity, income, credit profile, property, and debt obligations. A prequalification or initial estimate is not a loan approval.
Questions to ask before you apply
Ask how long the draw and repayment periods last, whether the rate is variable, what the rate cap is, and whether there are fees for opening, maintaining, or closing the line. Confirm the minimum payment calculation and whether the lender can reduce or suspend future draws. These details matter as much as the credit limit.
If you want to compare possible home equity financing paths without contacting lenders one by one, Debt Relief Alliance can help match qualified requests with participating lending partners. It is not a lender, bank, or mortgage broker, and nothing moves forward without your say. Partner terms, eligibility requirements, and any credit inquiry depend on the provider and the stage of the process.
The strongest HELOC decision is rarely the one with the biggest available limit. It is the one tied to a specific goal, a conservative borrowing amount, and a payment plan that still works if rates or household expenses rise.