A $40,000 renovation can look very different on paper depending on how you borrow against your home. The home equity loan versus HELOC decision is not simply about getting approved. It is about whether you need one predictable amount of money or flexible access to funds over time, and whether the payment risk fits your budget.
Both options use your home equity as collateral. That can make them useful for a major planned expense, but it also means missed payments can put your home at risk. The right choice depends on your purpose, income stability, timeline, and comfort with changing interest rates.
Home Equity Loan Versus HELOC: The Core Difference
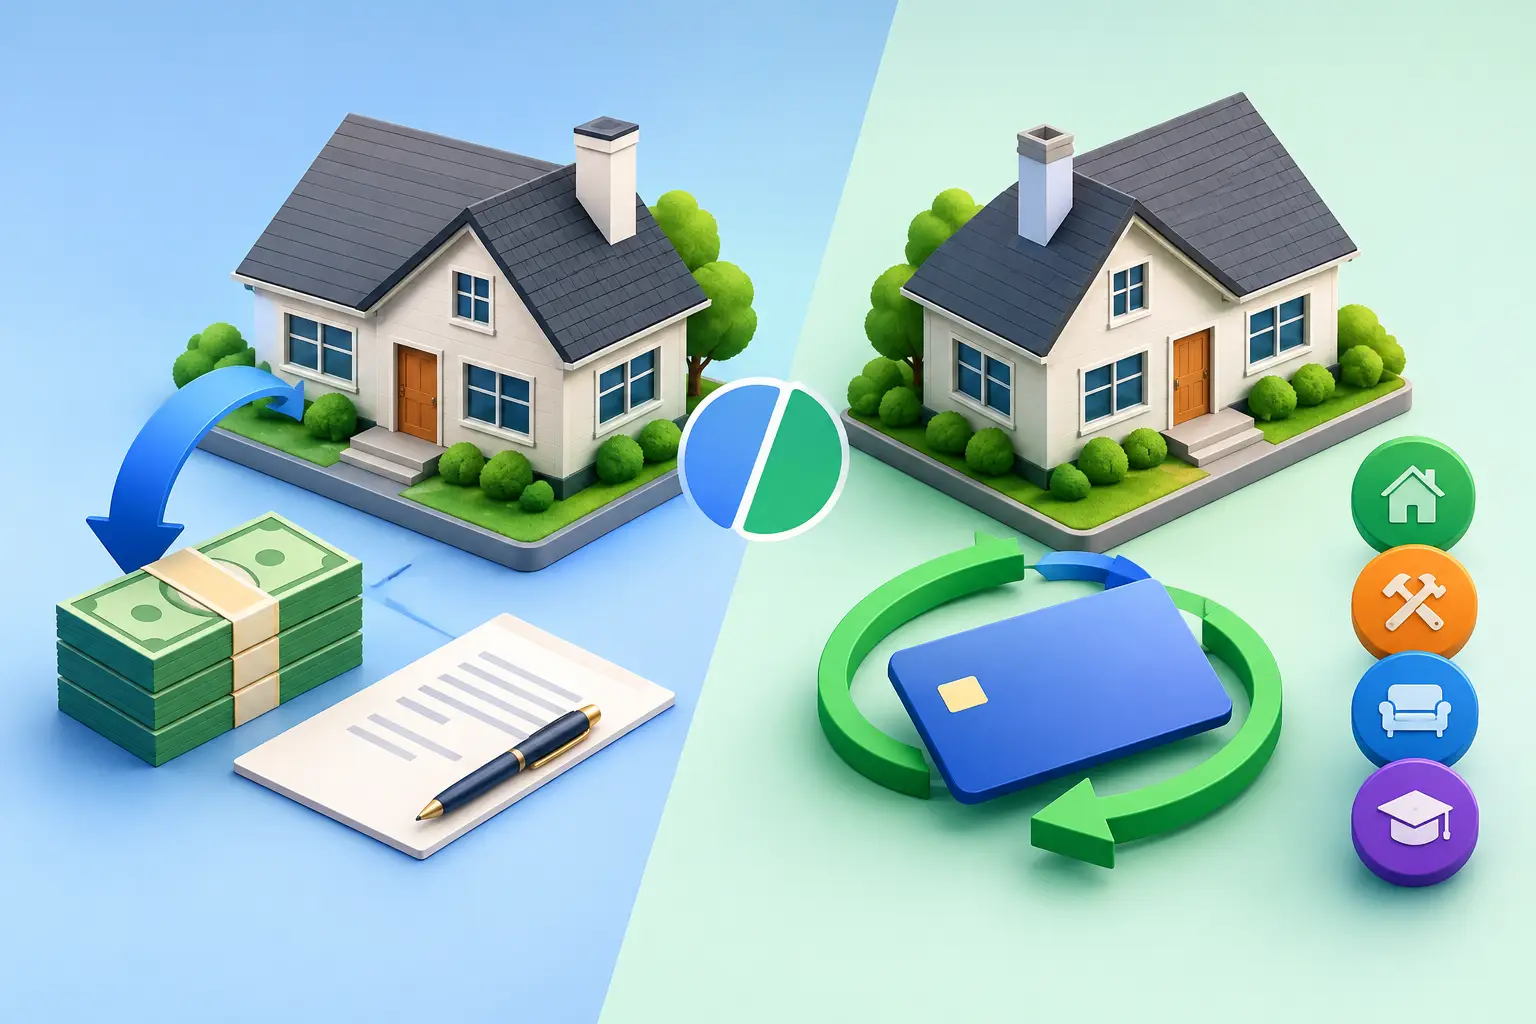
A home equity loan gives you a lump sum at closing. You generally repay it in equal monthly installments over a set term, often with a fixed interest rate. If you borrow $50,000, you receive $50,000 upfront and begin repaying that amount based on the loan's terms.
A home equity line of credit, commonly called a HELOC, works more like a revolving line. A lender approves you for a maximum limit, but you can draw only what you need during the draw period. You may borrow, repay, and borrow again, subject to the account terms and available credit.
That structural difference affects everything from your payment to your total interest cost. A home equity loan is generally built for a defined, one-time need. A HELOC is often better suited to expenses that arrive in phases or remain uncertain.
How repayment typically works
With a home equity loan, principal and interest are usually part of every scheduled payment from the start. A fixed rate and fixed term can make planning easier because the required payment normally stays the same.
A HELOC often has two stages. During the draw period, some lenders allow interest-only payments on the amount you have used. Once the repayment period begins, you can no longer draw funds and must repay principal plus interest. That payment can rise sharply, particularly if you made interest-only payments before repayment started.
HELOCs commonly have variable rates tied to a benchmark rate plus a lender margin. Your rate and payment can increase when market rates change. Some lenders offer fixed-rate conversion features for all or part of a HELOC balance, but availability and terms vary.
When a Home Equity Loan May Fit Better
A home equity loan may make sense when you know the exact amount you need and want a payment you can budget around. Examples include a completed contractor estimate, a one-time medical expense, or a large purchase with a clear final cost.
It can also be worth considering if rising rates are a concern. Locking in a fixed rate may provide more certainty than a variable-rate line, even if the initial HELOC rate appears lower. The trade-off is that you begin paying interest on the full loan amount right away, including any money you do not need immediately.
For debt consolidation, a home equity loan can create one set monthly payment. But the lower rate is not the only factor to consider. You may be turning unsecured balances, such as credit card debt, into debt secured by your home. Consolidation only helps if the new payment is affordable and you have a realistic plan not to rebuild the balances you paid off.
When a HELOC May Fit Better
A HELOC can be a practical option when the cost or timing of your project is uncertain. A multi-stage renovation is a common example. You might use funds for design and permits first, then draw more as construction invoices arrive. You only pay interest on the amount you actually use, not the full approved limit.
It may also work for homeowners who want a financing cushion for a planned purpose but do not want to take a large lump sum prematurely. Flexibility is the main advantage, not a reason to borrow without a clear repayment plan.
The trade-off is rate uncertainty. A HELOC payment can change even if you do not borrow additional money. Before accepting a line, ask how often the rate can adjust, whether there is a rate cap, and what your payment could look like if rates rise.
Compare More Than the Interest Rate
An advertised rate does not tell you the full cost or risk of either product. Compare the lender's complete terms before making a decision. Four questions can help you focus on what matters:
- Is the rate fixed or variable, and what could cause it to change?
- What are the monthly payment, repayment term, and total estimated finance charges?
- Are there closing costs, annual fees, inactivity fees, prepayment penalties, or early closure fees?
- What is the maximum combined loan-to-value ratio, and how much equity must remain in the home?
Your available equity is usually based on your home's current value, your first mortgage balance, and any other liens. Lenders also review factors such as credit history, income, debts, property type, occupancy, and their own underwriting guidelines. An online estimate or prequalification is not a final approval.
For a HELOC, ask whether the lender can reduce, freeze, or close the line under certain conditions. A line of credit is not the same as cash in a savings account. Lenders may have contractual rights to restrict future advances in situations described in the agreement.
Think Through the Payment Under Stress
The payment that works in a normal month may not work after a job change, higher insurance bill, or rate increase. Build your decision around the payment at a less comfortable, but plausible, scenario.
For a fixed home equity loan, review whether the required payment still leaves room for savings, routine repairs, taxes, and insurance. For a HELOC, calculate the payment after the draw period ends and at a higher interest rate than the one quoted today. If that future payment would strain your household budget, a smaller borrowing amount or a different financing structure may be safer.
Avoid using either option for everyday expenses that continue month after month. Borrowing against home equity can solve a short-term cash shortage while making a longer-term budget issue more serious. A clear use for the funds and a clear payoff path should come before an application.
How to Compare Options Without Rushing
Start by writing down your expected funding need, when you will need it, and the monthly amount you can comfortably repay. Then compare offers based on the same borrowing amount and repayment assumptions. A lender may offer attractive terms for one profile or property type but not another.
When exploring options through a matching service, confirm who will contact you, what information is being shared, and whether a hard credit inquiry is required before you proceed. Debt Relief Alliance is not a lender, bank, mortgage broker, or tax practitioner. It connects eligible consumer requests with participating third-party providers, while lenders make their own approval and pricing decisions.
A request to be matched may not require an initial hard credit inquiry, but a lender can require a hard inquiry when you choose to move forward with an application. Ask before authorizing one. There should be no confusion about the next step, the provider involved, or the terms you are considering.
A home equity loan can offer certainty when the expense is known. A HELOC can offer flexibility when it is not. Give the same care to the repayment plan as you give to the rate, and move forward only when the payment protects your household's breathing room.